How do I record a partial sale of startup shares in a tender or secondary?
Give each settled sale its own lot row. Log the original cost basis, acquisition date, share class, and vehicle (direct or SPV). Then log price per share, shares sold, fees and carry, gross and net proceeds, and settlement date. Split the sold slice from the leftover shares. Both keep the original acquisition date, so the sale does not restart the holding period on shares you keep, and leftover basis does not reset to the sale price. The election and fill process sits on startup secondary sale tracking.
To track a secondary stock lot after a tender, a Hiive- or EquityZen-style marketplace trade, or an SPV distribution, copy each cell from the settlement statement, K-1, or transfer-agent notice. Do not overwrite the original SAFE or preferred row. Do not paste a marketplace headline price onto leftover shares.
What this ledger is (and is not)
A secondary stock lot is one identifiable slice of a company position that changed because some of it sold, or because an SPV distributed cash or shares. Carta's secondary-market explainer (April 3, 2026) says no new shares are created in a secondary: an existing holder sells, and the cash goes to the seller, not the company. That is why the lot splits. Window, ROFR, and election versus fill stay on the process page.
This ledger is not a SAFE conversion worksheet. If the original instrument was a SAFE that later converted, keep that history on SAFE note tracking and point this lot at that row. Syndicate SPV tracking is the vehicle overlay (fees, carry, K-1s). This page asks whether this lot sat in that vehicle, and which dollars or shares came out.
Six columns on one lot
Open one row per lot that settled. Attach the settlement statement, the original wire, and the SPV notice if any. Name the lot by instrument, share class, and year (SAFE 2022, Series A Preferred 2023, SPV interest 2024) so two lots in the same company cannot overwrite each other.
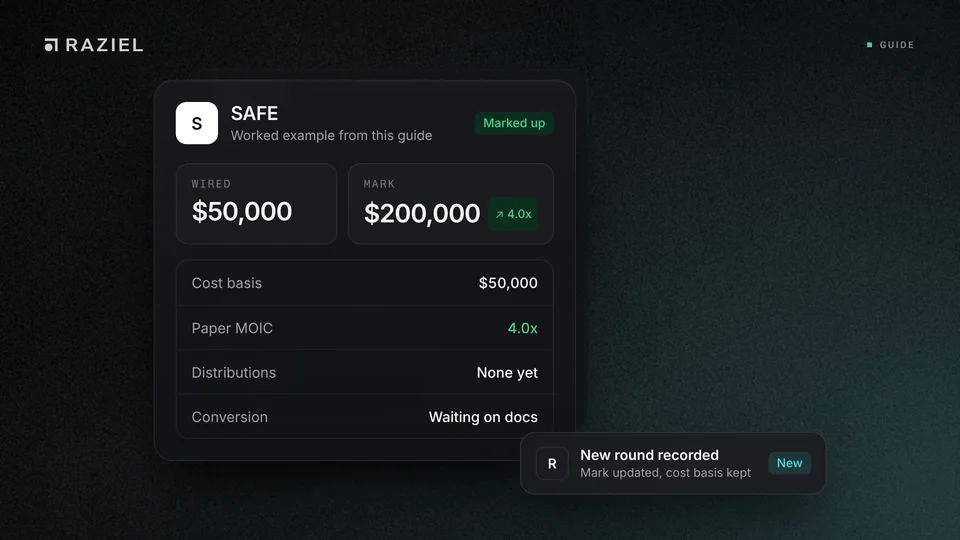
Cost basis of the lot. Copy original dollars in (wire plus costs), the acquisition date, and the share class. IRS Publication 551 (revised December 2025): stock basis is generally the purchase price plus costs of purchase, such as commissions and transfer fees. If you cannot identify which shares you sold, their basis is the basis of the shares you acquired first. A missing basis is 'missing', not a last-round mark.
Vehicle: direct vs SPV. Direct means your name (or your fund's name) is on the cap table. SPV means you own an interest in a vehicle that owns the shares. After a secondary the vehicle can distribute cash, distribute leftover shares in kind, or keep leftover shares inside the SPV. Log which happened. Do not treat SPV cash as a direct lot sale, or an in-kind distribution as cash in.
Fees and carry. Copy platform, broker, transfer, and legal fees on the sold slice. Copy SPV management fee and carry that hit this distribution, if the notice shows them. Net cash is gross proceeds minus those items. Do not invent a market fee percentage. If the notice is silent, mark the fee cell 'missing'.
Cash in on sale. Price per share, shares sold, gross proceeds, net proceeds, settlement date, and payer (company, third-party buyer, SPV, or marketplace). Cash in is the dollars that hit the account, not MOIC. Book the date cash arrived, not the date you elected.
Leftover shares. Quantity remaining, same original instrument, same original acquisition date (the holding period does not restart). Leftover lockup is a date on this remainder lot (copy the contract end from the PDF on lockup tracking; keep Rule 144 on Rule 144 tracking). If the program was oversubscribed, leftover is shares held minus shares filled, not shares held minus shares elected. Do not delete the original row to make the remainder look clean.
Realized vs residual MOIC. Realized MOIC on the sold slice is net cash in divided by allocated cost of the shares that sold. Residual MOIC on leftover shares is unrealized value divided by leftover cost. Do not blend them into one company-level multiple until you can see both. Raziel's MOIC calculator is the arithmetic. For timing disagreements, see MOIC vs IRR.
Hypothetical walkthrough (round numbers, not a study)
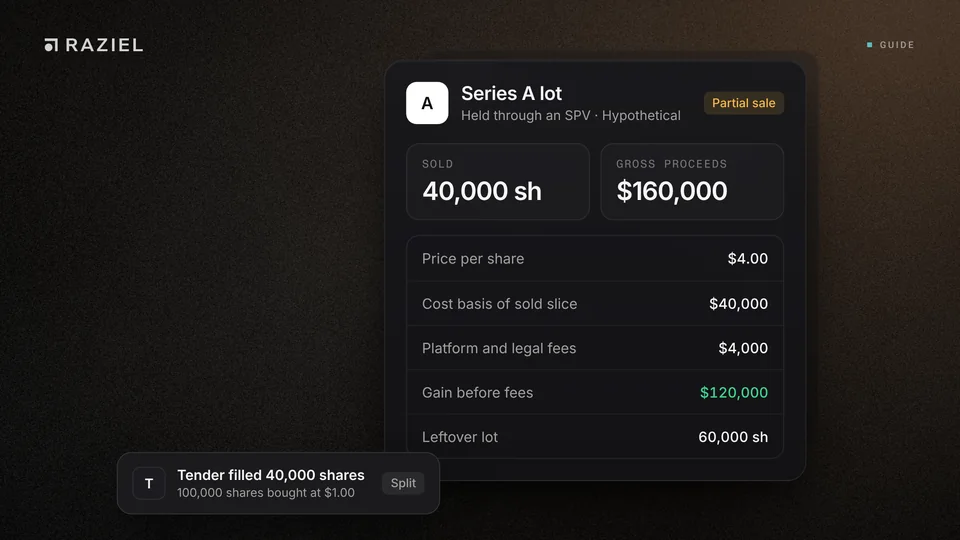
Not Raziel performance or a market average. You wired $100,000 into a Series A lot (100,000 shares at $1.00), held through an SPV. A company tender later fills 40,000 shares at $4.00. Gross proceeds $160,000. The SPV notice shows $4,000 of platform and legal fees. Allocated cost of the sold slice is $40,000, so the gain is $160,000 minus $40,000 = $120,000. For example, with 20% carry, the carry is 20% of $120,000 = $24,000. Net cash in is $160,000 minus $4,000 minus $24,000 = $132,000, or $3.30 per share sold. Realized MOIC is $132,000 / $40,000 = 3.3x. Leftover shares: 60,000, same Series A class and wire date. Leftover cost: $60,000. Residual MOIC is leftover mark divided by $60,000. Do not paste $4.00 onto the leftover 60,000 as a new cost basis.
If the original lot had been a SAFE, convert it on the SAFE tracking page first, then open this secondary lot against the converted share count. Do not run tender math on unconverted SAFE dollars as if they were shares.
Founders: send the lot facts when a tender or secondary hits
If you are the company running the tender (or approving a bilateral), investors cannot book the six cells without a clean update. Send the price, the window, who was eligible, election versus fill, settlement date, leftover lockup, and whether an SPV should expect cash or in-kind shares. Use Raziel for founders to send that update. Do not make investors reverse-engineer the lot from a screenshot.
When the ledger holds
The row holds if every cell is copied from settlement paper or marked missing. It breaks when you delete the original SAFE or preferred row, rebase leftover cost to the tender price, skip SPV fees, or treat process (ROFR, window, cutback) as if it answered basis and MOIC.
Where the leftover lot goes next
Leftover shares after a tender keep a contract lockup clock and a Rule 144 safe-harbor clock. Neither is the lot-split math on this page. Contract end date: lockup tracking. Safe harbor after the contract lifts: Rule 144 tracking. If the leftover lot still sits under an investor rights agreement, keep the demand and piggyback overlay on registration rights tracking, separate from the lot split. Before you sell part of a lot, check its QSBS holding period too: a partial sale can land on either side of a holding-period gate, so confirm the tax treatment with your tax advisor. Raziel tracks startup positions with MOIC and IRR. Create a free account to start, or see Raziel for startup investors.
This is not legal, tax, or investment advice. Raziel, Inc. does not provide it.