How do I track an SPV position after the syndicate closes?
Keep two linked records that share one cash history: the SPV (legal name, administrator, close date, commitment, wire date and amount, carry and fee terms) and the portfolio company (legal name and the instrument the SPV holds). What lands on each depends on what the SPV holds and sends you. Park each year's K-1 on the SPV record, because it comes from the vehicle, not the startup. If the manager opens a follow-on SPV, open a second record instead of overwriting the first. For capital calls, use how to log an SPV capital call.
Tracking SPV positions is post-close work: the special-purpose vehicle after it wires into the company, not the packet that formed it. Forming the group is covered in building a syndicate. AngelList’s help center says 20% carry is standard on its SPVs. If you only store the dollars you wired, that drag stays invisible until a distribution hits. For how SPV, fund, and direct checks into the same company should sit side by side, see SPV vs fund vs direct tracking.
Log the SPV and the company as linked records
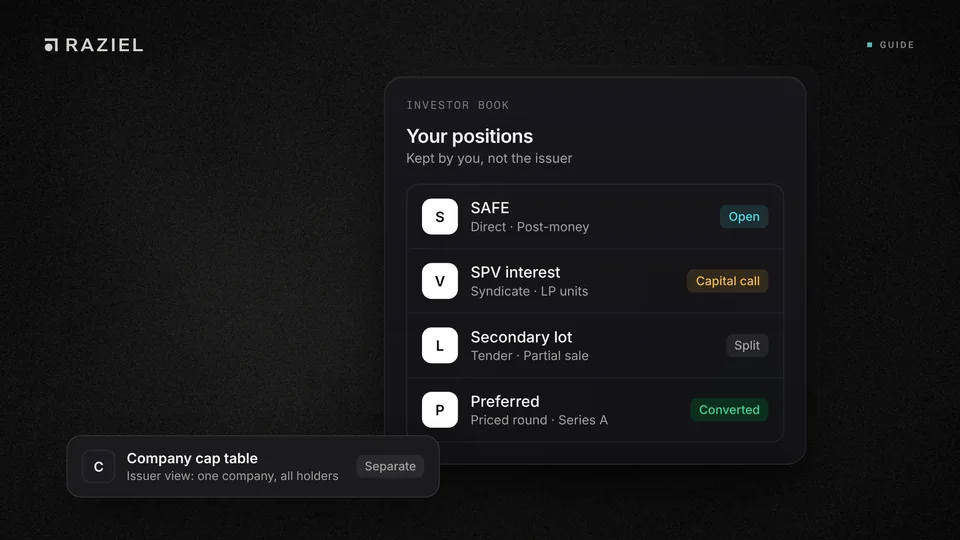
You subscribed into an LLC or limited partnership. That vehicle is the shareholder of record. AngelList says each deal is a separate vehicle, with its own setup cost and lifetime administration. Collapse the SPV name and the company name into one spreadsheet row and you cannot tell what you own from what the SPV owns.
Keep two linked records that share one cash history, in a spreadsheet or a free Raziel account:
The SPV. Legal name, administrator (AngelList, Sydecar, SPV Hub, or counsel), close date, your commitment, wire date and amount, and carry and fee terms from the deal page. When a notice asks for cash later, keep commitment, call, and wire as separate fields (see how to log an SPV capital call).
The portfolio company. Legal name, the instrument the SPV holds (SAFE, convertible, or priced equity), and any later round or mark the lead actually sent.
Roll company exposure up from the link. Do not post the same dollars on both rows. That parent-and-child book is how you track syndicate and SPV positions next to a direct check without double-counting cost basis.
Fees and carry sit on the vehicle
Setup fees and the lead’s carry are separate costs, and both sit on the vehicle. AngelList’s SPV pricing page, as of October 2026, lists an $8,000 setup fee plus a $2,000 blue-sky passthrough for a standard deal, with follow-on SPVs (same company, same syndicate, later round) at $5,000 plus $2,000. Those fees are prorated across LPs by investment amount and capped at 10% of the raise, excluding add-ons. Setup covers lifetime administration, investor K-1s, an LP portal, and distributions at no extra platform charge.
Carry is separate. AngelList’s SPV help article says the fund manager sets the percentage and that 20% is standard. In AngelList’s own LP example, a $5,000 commitment into a 20% carry vehicle that later distributes $100,000 leaves the LP with $81,000 after the lead’s $19,000 of profits. Sydecar, which takes no platform carry, states that the median carry on its SPVs is 15%, and that management fees are typically collected separately and do not reduce the carry calculation.
Copy those terms onto the SPV record on day one. AngelList’s LP dashboard already computes IRR and TVPI net of fees and carry. Individual valuations are private by default, delayed 90 days, and unlocked only by the fund lead. A locked portal line is a feed. It is not net ownership.
Worked example: gross vs net MOIC on a $25,000 SPV check
Illustrative example with made-up round numbers, not market data. Assumptions: $25,000 commitment, $1,000 prorated setup fee (4%, under AngelList’s 10% cap already cited on this page), $24,000 deployed, 20% carry on profit above the $25,000 contributed, no management fee, no hurdle. Documents may calculate carry differently.
Exit on deployed capital | Gross proceeds | Profit vs $25,000 | Carry (20%) | Net to you | Net MOIC |
|---|---|---|---|---|---|
1x | $24,000 | -$1,000 | $0 | $24,000 | 0.96x |
3x | $72,000 | $47,000 | $9,400 | $62,600 | 2.50x |
10x | $240,000 | $215,000 | $43,000 | $197,000 | 7.88x |
The company’s 3x shows up as 2.50x on your cash, which is why the SPV record stores fees and carry, not just the wire. Create a free account to keep fees and carry on the SPV record, or use Raziel’s MOIC calculator for the multiple math.
The K-1 comes from the SPV, not the startup
Most venture SPVs are pass-through entities. Sydecar says a vehicle must issue K-1s for every year in which a taxable event occurs. AngelList prepares and distributes K-1s at no extra cost to LPs, from the Taxes and Documents tab on the investor dashboard.
AngelList’s own calendar is the one to log: expected release dates post in late February; a packet of finalized or estimated K-1s in late March; finals for those estimates from April through August. You only receive a K-1 when there is taxable activity or it is the vehicle’s initial year. AngelList notes that SPVs that only invested in SAFEs or in equity of corporate entities often show as “not issuing.” That status is a field. Park the PDF on the SPV record and log its status on K-1 tracking for alternative investments. For the columns, copy the K-1 tracker template. The startup does not send this form.
Pro-rata is a second vehicle, not an overwrite
Sydecar’s investor-rights guide says pro-rata, when granted, belongs to the SPV as the legal investor, not to each LP personally. LPs participate only if the manager exercises on behalf of the vehicle, often by launching a follow-on SPV. AngelList prices that follow-on as a new vehicle on the same syndicate into the same company. Do not overwrite the first SPV row when a follow-on opens. Open a second SPV record, link it to the same company, and log whether you were offered the allocation and whether you wired.
Portals are feeds. Your ledger is the book.
AngelList’s LP portal and Sydecar’s investor dashboard are where documents and marks originate. They are not a book across platforms. To track SPV positions you actually own, export the file or download the K-1, attach it to the SPV record, and post only cash dates you can defend: the wire out, a distribution in, a follow-on you actually took. Without those dates, IRR is a guess even when a dashboard prints one.
A workbook holds this if the links hold: SPV open, company linked, one cash line dated to the wire, fees and carry on the vehicle, K-1 parked. It fails when the portal line is treated as net, the follow-on overwrites the first vehicle, and IRR is computed from a mark with no cash date.
After the SPV closes
Keep the SPV cash book first: commitment vs call vs wire on how to log an SPV capital call, then link the vehicle to the company. When the vehicle still holds shares after pricing, open the stock-exit clocks on those lots separately: lockup for the underwriter contract, Rule 144 for the safe harbor (do not apply the portfolio-company clock blindly to an LP interest in the vehicle; counsel owns that map), secondary stock lot for leftover tenders, registration rights for the Investors’ Rights Agreement overlay. Create a free account to start, or see Raziel for startup investors. Founders with an SPV on the cap table can use Raziel for founders.
This is not legal, tax, or investment advice. Raziel, Inc. does not provide it.